Buying a house comes with a pile of paperwork, and two terms keep popping up: inspection and appraisal. They sound alike, and plenty of first time buyers assume one covers the other. It doesn’t. A residential home inspection looks at the physical condition of the property, while an appraisal estimates what the property is worth. Knowing how each one works can save you money, stress, and a few awkward conversations with your lender. Let’s untangle the two so you know exactly what to expect before closing day.
What a Home Inspection Actually Covers
The Physical Condition of the House
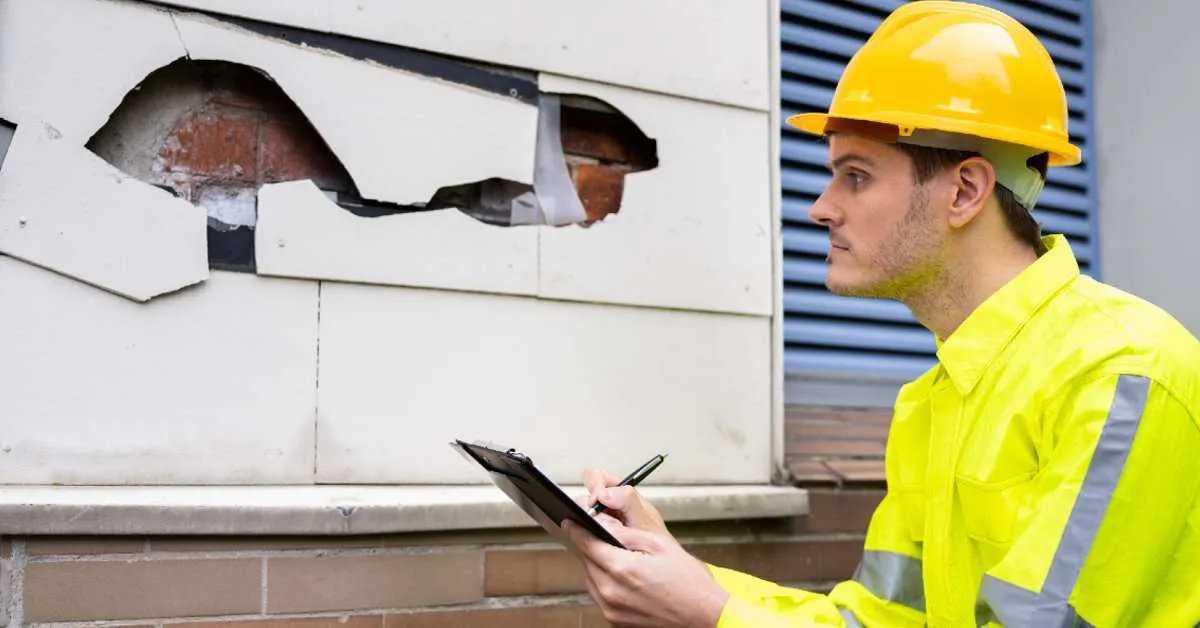
A home inspection is a visual, hands on review of a property’s major systems and structure. The inspector walks through the roof, foundation, plumbing, electrical panel, heating and cooling, attic, and visible walls. Think of it as a physical exam for your house. When my cousin bought her first place, the inspector spotted a slow leak under the kitchen sink that nobody had noticed in years. Most buyers see the inspection and appraisal as a package, but each has its own job.
What the Home Inspection Report Tells You
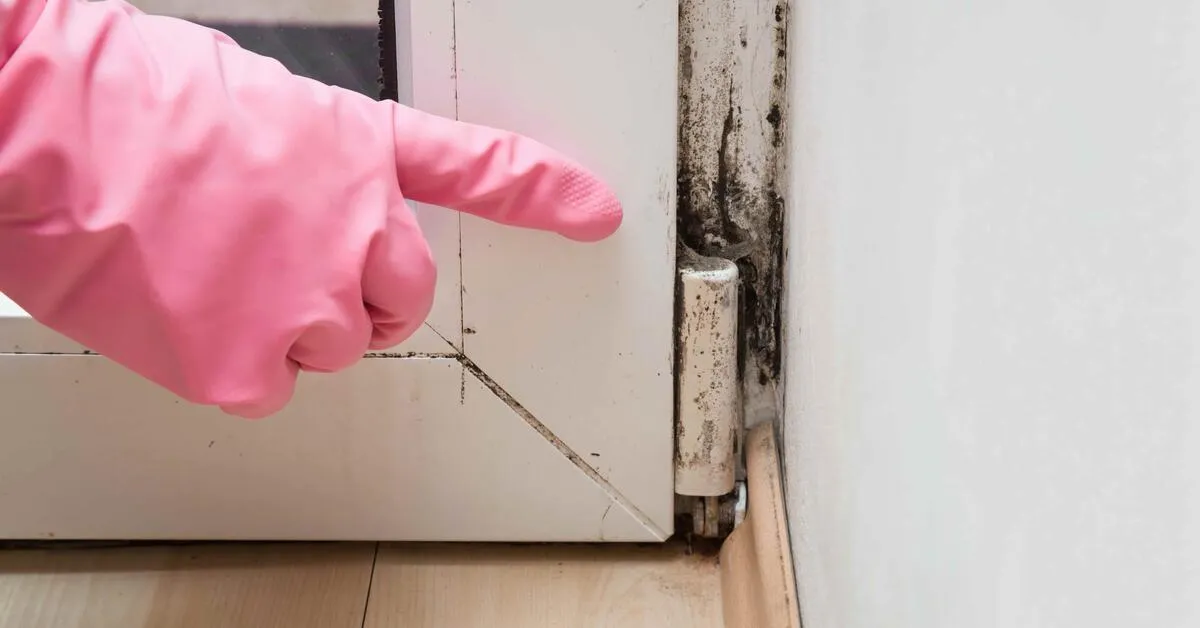
The home inspection report arrives within a day or two, usually with photos and notes. It ranks issues by urgency, so you can tell a cosmetic annoyance from a genuine safety concern. Buyers use it to negotiate price, ask sellers to fix items, or walk away.
How a Property Appraisal Works
The Goal Is a Home Value Assessment
A property appraisal is an independent opinion of market value, performed by a licensed appraiser. Your lender orders it to confirm the home is worth the loan amount. The appraiser compares recent sales of similar homes nearby, then adjusts for size, age, upgrades, and lot features. The result is a home value assessment that protects the bank, and you, from overpaying. Lenders treat inspection and appraisal as separate checkpoints.
What Happens When the Numbers Come Up Short
Sometimes the appraisal lands below the contract price. That is called an appraisal gap, and it can stall a deal. You can ask for a review, renegotiate with the seller, pay the difference in cash, or step back. Remember, the appraiser is not checking for hidden defects. A great appraisal can still sit on top of a leaky roof.
Inspection vs Appraisal: The Real Difference
Purpose and Who Benefits
The difference between inspection and appraisal comes down to purpose. An inspection protects the buyer by exposing the condition of the home. An appraisal protects the lender by confirming value. One answers “Is this house sound?” and the other answers “Is this price fair?” Neither one can replace the other.
Cost, Timing, and Who Hires Them
Buyers typically hire and pay for the inspector, often scheduling it within the first week after an offer is accepted. Lenders order the appraisal, though buyers usually cover the fee at closing. An inspection takes a couple of hours on site, while an appraiser may spend under an hour walking the home and then days researching comparable sales. Timing matters, so book early. Both reports shape your final decision, just in different ways.
Do You Need Both Before You Buy?
When Skipping One Gets Risky
In most cases, yes. A cash buyer might skip the appraisal, but skipping the inspection is a gamble. A financed purchase almost always requires the appraisal, yet the inspection stays optional on paper, and that is where buyers get burned. Imagine paying full price for a house with a cracked foundation because the paperwork looked tidy. Pairing inspection and appraisal gives you the full picture: condition and value together.
Tips for Getting the Most From Both
A few simple habits make both steps run much smoother:
- Attend the inspection and ask questions as you go.
- Read the full report, not just the summary page.
- Gather recent comparable sales before the appraisal.
- Keep records of upgrades to share with the appraiser.
- Schedule both early to protect your closing date.
Frequently Asked Questions
What is the difference between inspection and appraisal?
An inspection evaluates the physical condition of a home, covering structure, systems, and safety concerns, and it protects the buyer. An appraisal estimates market value for the lender. One focuses on condition, the other on price, so they serve completely different purposes in a purchase.
Can a home appraisal replace a home inspection?
No. A home appraisal only estimates value and does not look for hidden defects in plumbing, wiring, or the roof. Only a thorough inspection reveals those issues, so relying on the appraisal alone leaves you exposed to costly surprises and stress after you move in.
Who pays for inspection and appraisal costs?
Buyers usually pay for both services. The inspector is hired directly by the buyer, while the lender orders the appraisal and passes the fee along at closing. Costs vary by location and property size, so ask for quotes early in the process and compare them.
What happens if the property appraisal is lower than the offer?
The deal can stall, since lenders only finance up to the appraised value. You may negotiate a lower price with the seller, cover the gap in cash, request a reconsideration, or cancel under your contract terms. A home value assessment backed by comparable sales helps.
How long do inspection and appraisal appointments usually take?
Most inspections last two to three hours depending on the size and age of the home. The appraiser’s visit is usually shorter, though the written report may take several days. Plan ahead so both appointments fit within your closing timeline and avoid last minute delays.
Make Confident Choices With Both Reports
Smart buyers treat inspection and appraisal as teammates rather than rivals. One reveals what the house is made of, the other reveals what it is worth, and together they help you buy with open eyes. Skip either step and you are guessing on the biggest purchase of your life. Mastering inspection and appraisal early keeps closing day calm. Ready to schedule a thorough inspection and move forward with confidence? Book With Liberty Home Inspections today and get clear answers before you sign anything.